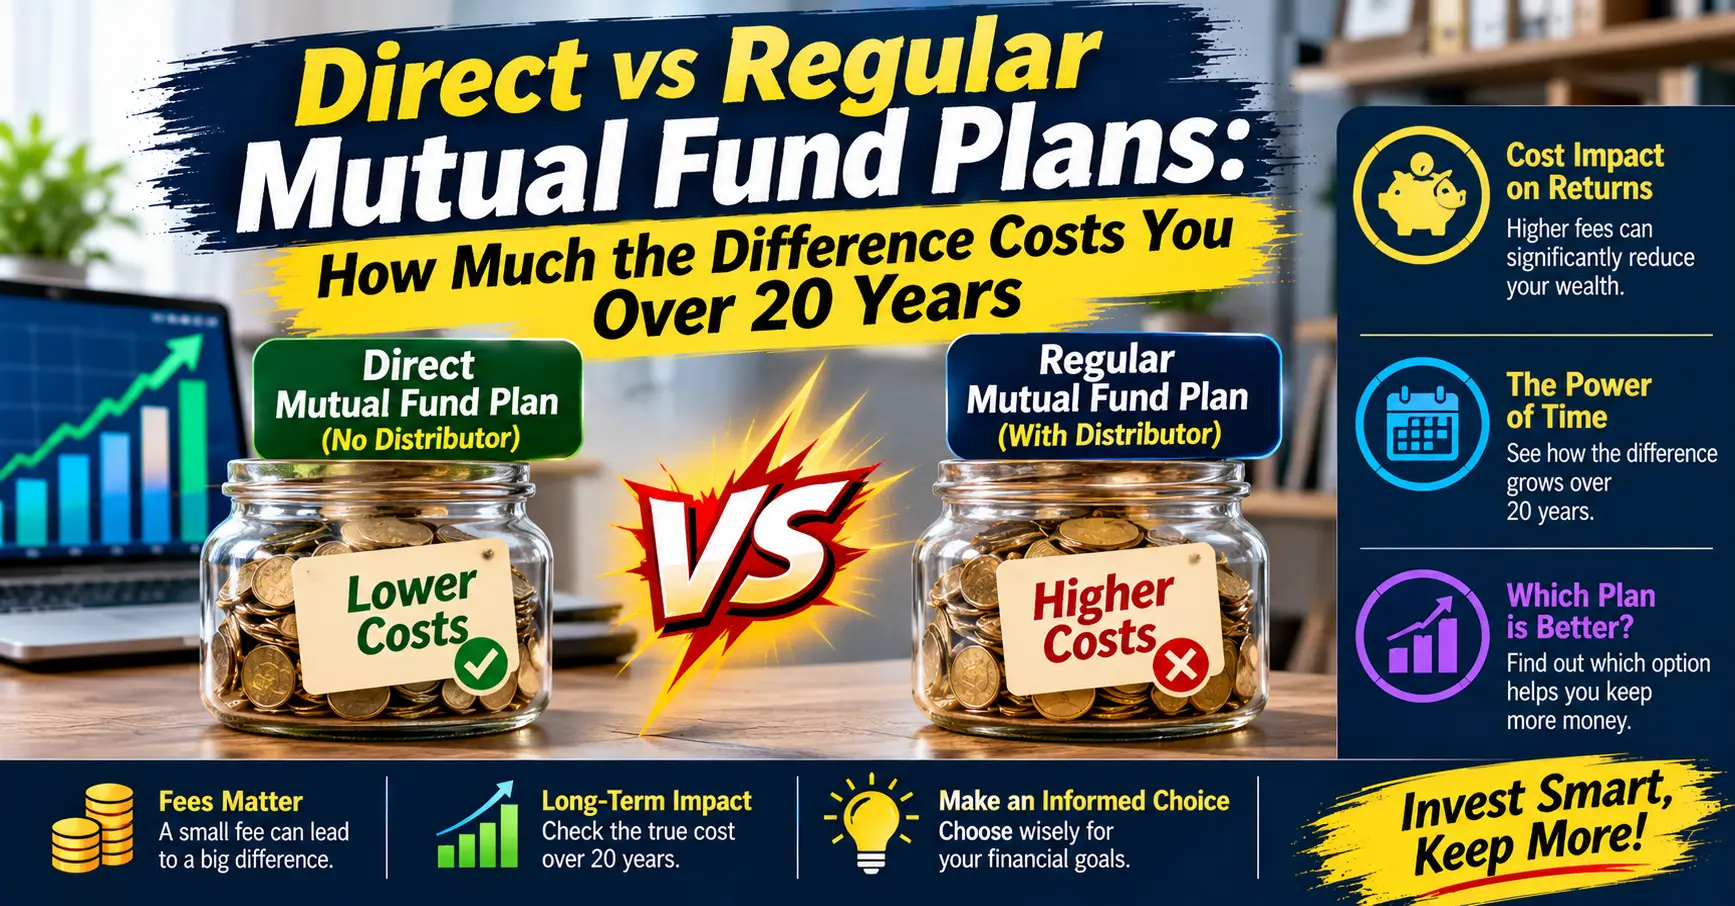
When investing in mutual funds, you may come across two options: the Direct Plans and Regular Plans. While both plans invest in the same mutual fund scheme, they differ in how you buy them and the associated costs. Initially, the difference between the two may appear minor, but it can add up to be significant in the long run.
Let’s explore the differences between the two plans and how much they cost.
Direct Mutual Fund Plan
A direct mutual fund scheme involves investing directly into the Mutual Fund scheme itself without any assistance from either the distributor or the agent. Since there is no distributor commission, the expense ratio of a Direct Mutual Fund Scheme is relatively low.
This is because the expense ratio is the charge imposed on the management of money invested in the mutual fund. It forms part of the net asset value of the mutual fund.
People who are comfortable researching mutual funds and managing their investments usually prefer direct mutual fund schemes.
Regular Mutual Fund Plan
A regular mutual fund scheme is bought via a distributor, financial adviser, bank, or investment platform that offers distribution services. The distributor earns a commission from the mutual fund company for attracting and serving clients.
The commission forms part of the costs involved in the plan; hence, regular schemes have higher expense ratios compared to direct ones.
For clients who require assistance in picking the funds and the investment process, among other things, a regular scheme might be helpful. However, this service comes at an added cost.
Direct vs Regular Plans: The Difference
Both direct and regular mutual fund schemes have an identical underlying portfolio and the same fund manager. The investment objective and investment strategy are also the same for both schemes.
However, the difference between the two lies in the expense ratio. The expense ratio refers to the cost incurred for the management of the fund annually. In the case of the direct mutual fund plan, the investors directly acquire units of the scheme from the AMC, and the distributor does not come into the picture. Hence, the expense ratio in this case is relatively low.
On the other hand, in the case of regular mutual fund schemes, the units are bought from the distributors or financial advisors, who receive their commission as part of the expense ratio. Moreover, regular mutual fund schemes also provide assistance in fund selection and queries related to investments.
How Much Can the Difference Cost You Over 20 Years?
Small differences in the annual cost can make a significant impact on the net worth created over a period of time, since higher costs imply a lower investment amount to benefit from the power of compounding.
For instance, let us assume that one invests ₹10,000 every month using an SIP for 20 years. Thus, the total investment made by the investor will be ₹24 lakhs. Let us also assume that the fund gives an annual return of 12% before costs. The cost for the direct plan is 0.5% and for the regular plan is 1.5%. After the cost, the annual return assumed for both plans would be 11.5% and 10.5%, respectively.
Accordingly, after 20 years, the investment would yield approximately ₹86.6 lakh in the case of the direct plan and ₹76.8 lakh in the case of the regular plan. This shows that there is a difference of about ₹9.8 lakh after 20 years.
Which Plan Should You Should Choose
The right choice depends on your comfort in managing your investments.
The direct plan works best for those who can do some homework on mutual funds, know their financial goals, and can review their portfolio on their own. The regular plan can be beneficial for those investors who need help or guidance from distributors/advisors.
Conclusion
The difference between a direct and regular mutual fund may seem insignificant as an annual fee but can prove substantial over a period of 20 years. A smaller expense ratio will mean that a larger amount of your funds can stay invested through the power of compounding. Meanwhile, professional advice will come in handy if one is looking for assistance in making financial decisions. What matters is that the investor realizes what he or she is paying for and whether it’s worth the extra cost. It is vital to analyze the plan cost and make an appropriate decision.
FAQs
What is the difference between direct and regular mutual fund plans?
Investors can buy direct plans directly from the mutual fund company, whereas regular plans are purchased from distributors or financial advisers. Direct and regular plans both invest in the same fund using the same strategy. However, direct plans are relatively more economical as they do not charge distributor commissions.
Why do direct plans have a lower expense ratio than regular plans?
As there is no role for the distributor in direct plans, they do not have any distributor commissions within their expenses. On the other hand, regular plans include this distributor commission within the expense ratio of the plan.
How much more can you earn from a direct plan over 20 years?
This depends on the gap between the expense ratios and fund performance. In one scenario, investing ₹10,000 per month for 20 years can lead to a gap of around ₹9.8 lakh, given a particular rate of return. Please note that this is just an estimate, and there are no guarantees for the actual rate of return.
Are direct plans now the default option on mutual fund platforms?
Direct plans may not be the default plan on all mutual fund websites. There are websites that offer both kinds of plans. Therefore, investors need to see which plan they are opting for when investing.
If you need guidance on how to start your stock market journey, how much capital is enough to begin with, how to do smart investing, or how to take informed stock market decisions, you can join Strategic Alpha’s ‘The Conviction Club’. This is a membership program, especially curated to help investors become aware and knowledgeable about stock market trends, news, and technical aspects, so that they can become their own experts.
Our YouTube channel, weekly webinars, and digital resources available on the website can help you learn the basics of the stock market. For regular updates on trends, one-to-one sessions with experts, and detailed learning modules, you can join the Conviction Club, which is the online community of like-minded investors sharing knowledge and thoughts to grow together.
Subscribe to the Strategic Alpha Newsletter now to get the latest updates about weekly webinars.
Join Me On My Telegram Channel Where I Share Much More Value Adding Knowledge Of Investing/ Trading: Click Here
Also, Don’t Forget To Follow Us On Our Social Media Accounts:
Facebook: https://www.facebook.com/strategicalpha/
Instagram: https://www.instagram.com/strategicalpha/
Twitter: https://twitter.com/suyog_dhavan
YouTube: https://bit.ly/2IIqztO
Disclaimer: Strategic Alpha and Suyog Dhavan are not SEBI-registered investment advisor. The content provided is purely for educational purposes and should not be construed as financial or investment advice. Viewers are encouraged to conduct their own research or consult with a SEBI-registered professional before making any investment decisions.